Transfers of Equity: The 2026 Guide to Changing Property Ownership

What if the simple act of adding a partner to your property title actually triggered a tax bill worth thousands of pounds? Many homeowners discover too late that changing who owns their home is rarely just a matter of swapping names on a document. With approximately 30% of property transactions in England and Wales falling through before completion, the stakes for getting transfers of equity right have never been higher. Whether you're navigating a relationship breakdown, getting married, or gifting a share of your home to a family member, the legal landscape in 2026 requires a proactive and precise approach.
It's completely natural to feel overwhelmed by the prospect of negotiating with mortgage lenders or worrying about the latest Stamp Duty Land Tax thresholds. You want a transition that's handled with care and transparency, rather than one bogged down by jargon and technical delays. This guide is designed to be your professional conveyancing roadmap. We'll show you how to master the legal complexities of changing ownership while minimising your tax liability and protecting your interests. From understanding the Land Registration Fee Order to securing lender consent, we provide the clarity you need for a smooth, secure transfer of title.
Table of Contents
What is a Transfer of Equity and Why Might You Need One?
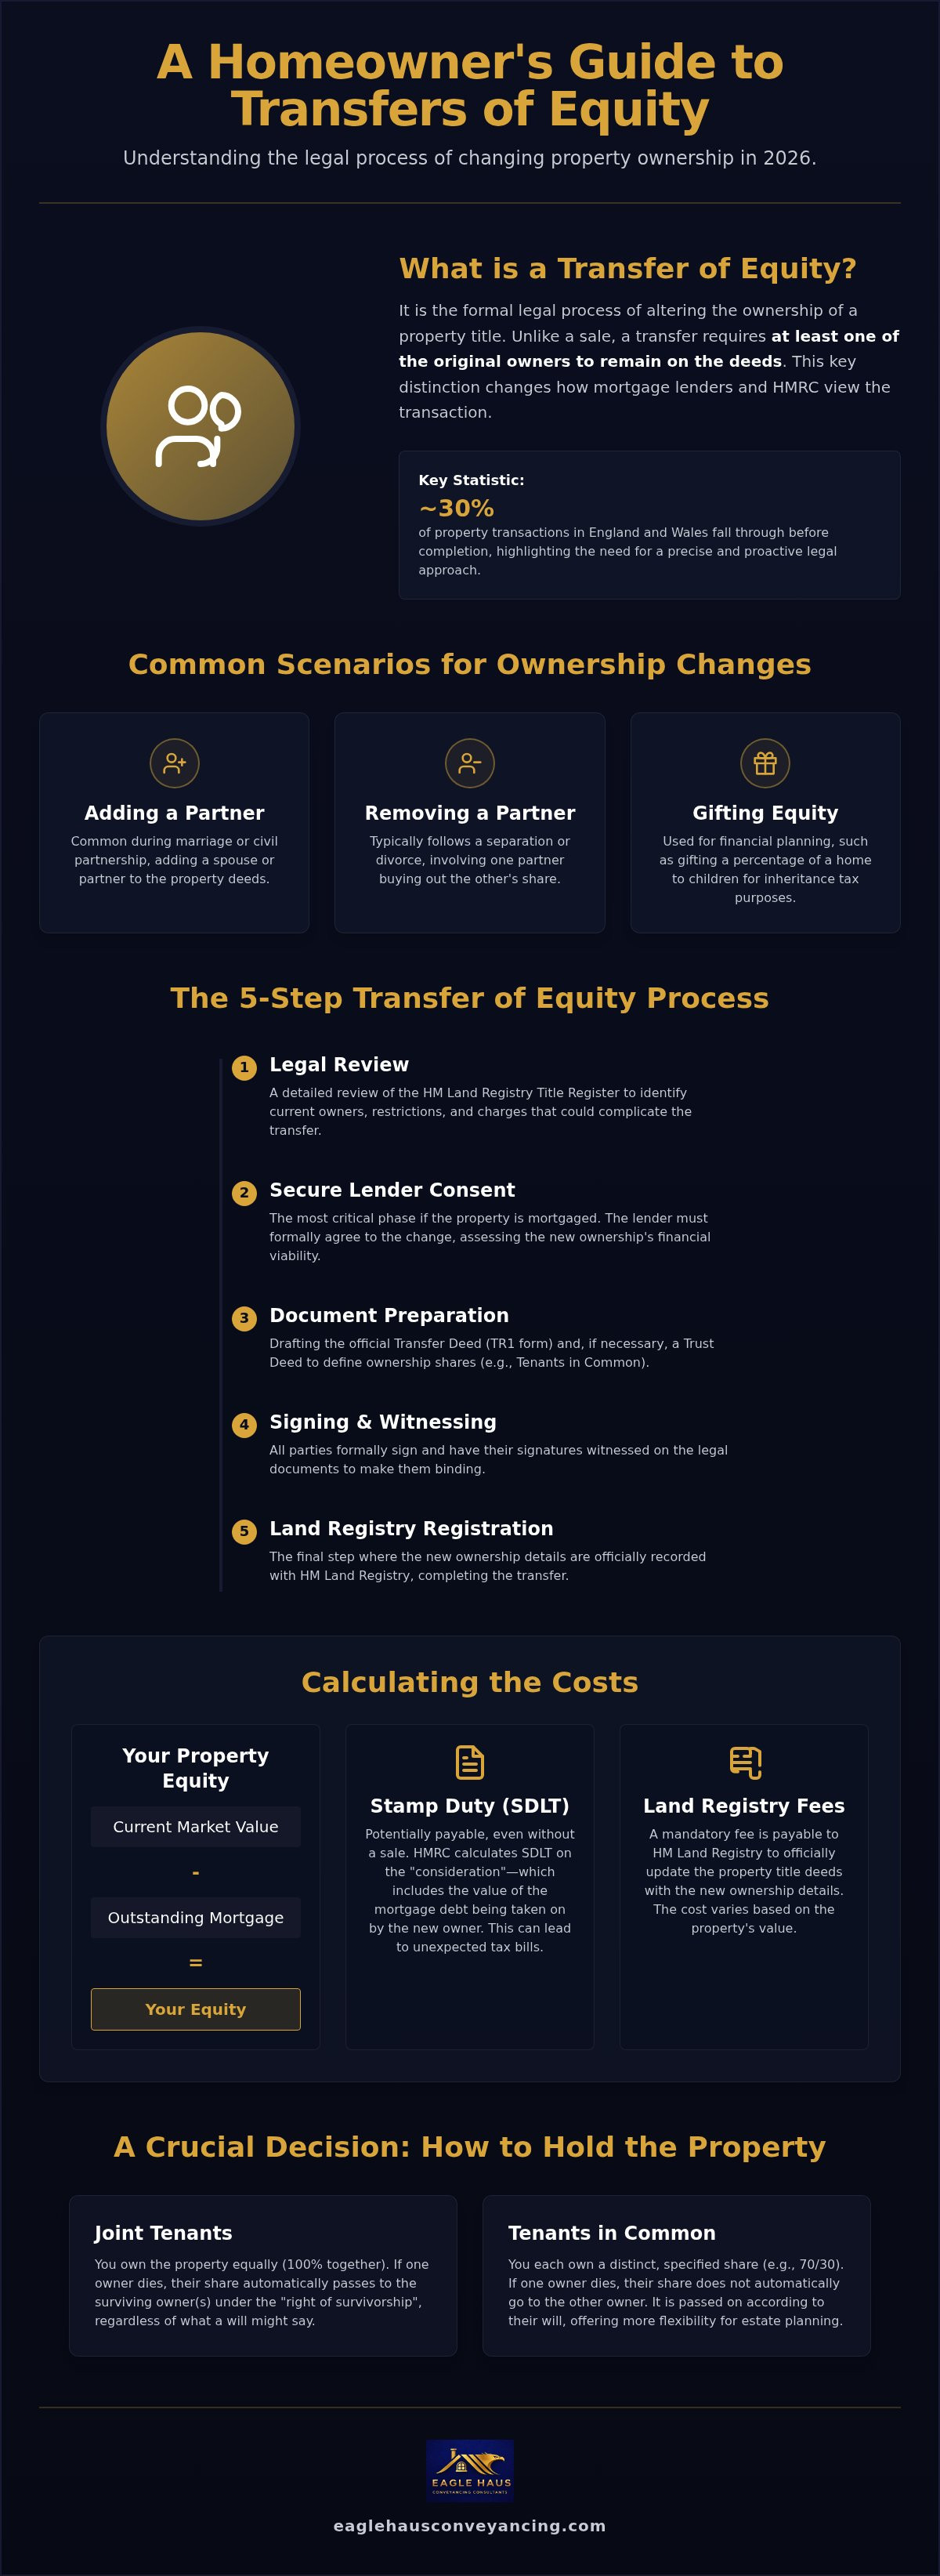
Many homeowners assume that changing names on a property deed is a simple administrative task. In reality, What is a transfer of equity? It's the formal legal process of altering the ownership structure of a property title. Unlike standard residential purchases and sales, where a property changes hands entirely, a transfer requires at least one of the original owners to remain on the title. This distinction is vital because it changes how mortgage lenders and HMRC view the transaction compared to a traditional sale.
Life moves fast, and your property ownership often needs to keep pace. You might be getting married and want to add your spouse to the deeds, or perhaps you're navigating a separation and need to remove a former partner. Beyond personal changes, many clients use transfers of equity for strategic financial planning. This includes moving a property into a limited company for tax efficiency or gifting a percentage of a home to children whilst retaining a right to live there. At Eagle Haus Conveyancing Consultants, we provide the legal oversight for these transitions through our partnership with the regulated firm Taylor Rose, ensuring every detail is handled with professional precision.
The Definition of Property Equity in 2026
Equity isn't just a financial buzzword; it's the actual value you hold in your home. To calculate it, you subtract your outstanding mortgage balance from the current market value. This figure dictates the complexity of your legal transfer. If there's a mortgage involved, the "consideration" includes the value of the mortgage debt being taken on by the new owner. This is the figure HMRC uses to decide if you owe Stamp Duty. Understanding this calculation early helps you avoid unexpected bills later in the process.
Typical Scenarios for Ownership Changes
Most ownership changes fall into three categories. Adding a partner often involves deciding between "joint tenants" or "tenants in common", which affects how the property passes on if one owner dies. Removing an owner, frequently following a relationship breakdown, involves "buying out" the other person's share and requires a formal release from mortgage obligations. Finally, family gifting allows you to pass equity to the next generation. This is a common tool for inheritance tax planning in Staffordshire and the West Midlands, though it requires careful legal drafting to protect all parties involved.
The Step-by-Step Transfer of Equity Process
Moving from the "why" to the "how", the process begins with a detailed forensic review of your HM Land Registry Title Register. Eagle Haus Conveyancing Consultants identifies all current owners and checks for any restrictions, charges, or "notices" that might complicate the change. Pinpointing these details early prevents last-minute hitches that could stall the transition. Once the legal scope is clear, we move to the most critical phase: securing lender consent.
If your property is mortgaged, your bank is a silent but powerful partner in the transaction. They must formally agree to any change in ownership because it alters their security. This isn't just a tick-box exercise; the lender will assess the "new" ownership structure to ensure their interests remain protected. If you're removing a partner, the bank needs proof that the remaining owner can handle the repayments alone. Through our partnership with the regulated firm Taylor Rose, Eagle Haus Conveyancing Consultants manages these communications proactively to keep the process moving forward.
After consent is granted, we move into the document preparation phase. We'll draft the Transfer Deed, known as the TR1 form, which is the legal instrument that officially moves the equity. If you're changing how you hold the property, perhaps moving from joint tenants to "tenants in common" to protect specific inheritance shares, we'll also prepare a Trust Deed. Once all parties have signed and witnessed the documents, we complete the process by registering the new ownership details with HM Land Registry.
Dealing with Mortgage Lenders and Consent
Lenders treat transfers of equity as a fresh lending risk. If you're removing a name, the person leaving must be granted a "Release of Liability" to ensure they aren't pursued for debt in the future. This protects both parties and provides a clean break. Should your current lender refuse the transfer due to affordability criteria, you might need to explore residential purchases and sales logic to find a new mortgage provider that fits your updated circumstances.
Identity Verification and Anti-Money Laundering
To keep your transaction secure and swift, we use modern digital ID checks. This replaces the old-fashioned requirement to bring physical passports into an office. These checks are mandatory under SRA and Land Registry standards to prevent property fraud. If one party isn't represented by Eagle Haus Conveyancing Consultants, they'll need to have their identity verified by their own solicitor or via an ID5 form to satisfy the Land Registry. We ensure all parties meet these compliance standards early to avoid delays at the point of completion. For a streamlined experience, speak with our consultants about starting your digital onboarding.
Calculating the Costs: Fees, Taxes, and SDLT
Budgeting for transfers of equity involves more than just the solicitor's fee. You need a clear view of the total investment to avoid surprises during the process. Eagle Haus Conveyancing Consultants prioritises fixed-fee transparency for residential conveyancing, provided through our regulated partner Taylor Rose. This approach ensures you know exactly what you're paying for legal expertise from the outset, allowing you to focus on the transition itself rather than worrying about escalating costs.
Beyond legal fees, you'll encounter disbursements. These are third-party costs we pay on your behalf to complete the legal work. The most significant is the HM Land Registry fee, which is dictated by the Land Registration Fee Order 2024. For applications submitted electronically, these fees are tiered based on the value of the share being transferred. For example, a transfer valued between £200,001 and £500,000 currently incurs a fee of £330, whilst values between £100,001 and £200,000 cost £230. We also handle smaller essential costs, such as office copy entries to verify the current title and bankruptcy searches for any new owners.
Stamp Duty Implications for Transfers
Stamp Duty Land Tax (SDLT) is often the largest expense, but it's also the most misunderstood. HMRC calculates tax based on "consideration", which isn't just the cash changing hands. It also includes the share of any outstanding mortgage that the new owner is taking on. If you're adding a partner to a property with a £400,000 mortgage, their consideration is £200,000. Under current rates, the 0% threshold sits at £125,000. In this scenario, they'd pay 2% on the portion between £125,001 and £200,000. However, if the transfer is the result of a court order in divorce proceedings, it's typically exempt from SDLT entirely.
Capital Gains Tax (CGT) Considerations
If you're transferring a share in a second home or a buy-to-let property amongst family members, Capital Gains Tax may apply. HMRC generally uses the "market value" rule for these transactions, even if you're gifting the share for free. For the 2026/27 tax year, the annual exempt amount is £3,000 per individual. Gains above this are taxed at 18% for basic rate taxpayers and 24% for higher rate taxpayers on residential property. Because these rules are complex, we always recommend seeking independent tax advice to sit alongside our legal work. This ensures your restructuring is as tax-efficient as possible whilst remaining fully compliant with current regulations.
Navigating Complex Scenarios: Remortgages and Portfolios
While many people view transfers of equity as a standalone task, property investors often see them as part of a larger financial restructure. It's rare that a change in ownership happens in a vacuum. Often, it's the perfect moment to reassess your current mortgage deal or move assets into a more tax-efficient corporate structure. At Eagle Haus, we specialise in these multi-layered transactions, providing the expert legal oversight needed to coordinate between lenders, shareholders, and original owners. We operate as a trading name of TRW Legal Consulting Ltd, with all legal services provided via the regulated firm Taylor Rose, giving you the security of a large firm with the personal touch of a boutique partner.
Remortgaging Whilst Transferring Equity
Combining a title change with a remortgage offers what we call the "Double Benefit". You update your ownership structure and secure a more competitive interest rate at the same time. This approach is highly efficient but requires a solicitor who sits on both the client's and the lender's panels. By handling both elements simultaneously, we help you avoid paying two separate sets of legal fees and prevent the delays that occur when two different firms try to coordinate completion. If you're an investor looking to optimise your portfolio, working with specialist buy to let remortgage solicitors ensures that the transfer of title aligns perfectly with your new lending terms. This streamlined process is particularly useful when you need to release capital from the property to pay off a departing owner.
Investor Strategies: Limited Company Transfers
Property investors in Wolverhampton, Birmingham, and across Staffordshire are increasingly moving personal property into limited companies. This "Company Purchase" process is a specific type of transfer that requires meticulous documentation to satisfy commercial lenders. The requirements are often higher than standard residential deals, involving personal guarantees and complex corporate resolutions. In situations where a co-owner needs a fast buy-out to settle a debt or fund a new project, we can facilitate bridging loans to provide the necessary liquidity before a long-term mortgage is finalised. This proactive approach helps you maintain momentum in your investment strategy without being held back by traditional banking delays. Our team provides the specialist expertise needed to manage these commercial pressures whilst ensuring your personal interests remain protected throughout the restructure. To discuss your property portfolio strategy with a modern legal partner, reach out to us for a transparent quote.
Why Eagle Haus is Your Partner for Transfers of Equity
Eagle Haus isn't your typical detached legal service. We've built our reputation on being a modern professional guide for homeowners and investors alike. When you're managing transfers of equity, you don't just need someone to file paperwork; you need a partner who anticipates the lender's next move. We operate as a trading name of TRW Legal Consulting Ltd, with all our regulated legal services provided through the established firm Taylor Rose. This partnership gives you the best of both worlds: the personalised, boutique attention of a local consultant and the robust security of a nationally recognised firm.
Our approach to residential purchases and sales is designed to eliminate the "legal black hole" that so many clients fear. We use tech-savvy communication tools to keep you updated in real-time, ensuring you never have to chase us for a status report. By prioritising transparency and speed, we reduce the stress that often accompanies major life transitions. Whether you're in the middle of a relationship change or a financial restructure, we ensure the legal side of your property stays on track.
A Modern Approach to Traditional Law
We believe that legal advice should be accessible and jargon-free. You'll have direct access to consultants who take the time to understand the specifics of your situation, whether you're adding a partner to your home or restructuring a portfolio. We proactively manage lender requirements from the start, which is the most common cause of completion delays. By identifying potential hurdles early, we keep you in total control of your property journey without the need for archaic legalese.
Serving Our Local Community
Unlike national firms that offer generic, impersonal services, we have deep roots in the West Midlands. We understand the specific property trends and Land Registry nuances across Staffordshire, Walsall, and Shropshire. Our team has extensive experience working with local families and investors in Cannock and Telford, providing a level of context that national "call centre" firms simply can't match. We're committed to supporting our local community with reliable, forward-thinking conveyancing that prioritises your peace of mind. If you're ready to move forward with confidence, you can start your transfer of equity with a professional quote today.
Secure Your Property's Future with Confidence
Changing the ownership structure of your home is a strategic financial move that requires precision and care. As this guide has shown, successful transfers of equity rely on navigating lender requirements and tax thresholds with a proactive mindset. By preparing for these complexities early, you can avoid unnecessary delays and protect your investment for years to come.
Eagle Haus is here to act as your modern professional guide through every stage of the process. We combine deep local knowledge of the West Midlands with the regulated security of our partner firm Taylor Rose. Our tech-savvy approach and commitment to frequent communication ensure you're never left in the dark. We focus on making your transition as smooth as possible through our streamlined digital onboarding system. If you're ready to master the legal side of your property title, Get a Transparent Transfer of Equity Quote from Eagle Haus today. It's time to move forward with a partner who prioritises your peace of mind.
Frequently Asked Questions
Do I need a solicitor for a transfer of equity if there is no mortgage?
Yes, you still need a solicitor to ensure the change is legally binding and the Land Registry is updated correctly. Even without a lender's involvement, we must draft the Transfer Deed (TR1) and verify that all parties understand the tax implications. Handling this professionally prevents future disputes and ensures that your property's title remains clean if you decide to sell or remortgage later on.
How long does a transfer of equity usually take to complete in 2026?
A simple transfer typically takes between 4 and 6 weeks to complete. This is significantly faster than a standard residential sale, which currently takes 12 to 16 weeks in 2026. However, if you have an existing mortgage, the timeline depends on how quickly your lender provides written consent. We use digital onboarding and electronic submissions to keep the process moving as quickly as possible for our clients.
Can I transfer equity to my child as a gift?
You can gift equity to your children, but you must consider the tax consequences. HMRC usually calculates Capital Gains Tax based on the property's market value, even if no money changes hands. Additionally, if you don't survive for seven years after the gift, the value may still be subject to Inheritance Tax. We recommend seeking independent financial advice whilst we handle the legal transfer of the title deeds for you.
What happens to the transfer of equity if my partner refuses to sign?
If a co-owner refuses to sign the necessary documents, the transfer cannot proceed through the standard route. In these cases, you may need to apply for a court order to force the transfer or sale of the property. This is common during relationship breakdowns where one party is reluctant to leave the title. Our team can guide you through the legal options available to resolve these disputes effectively.
Will I have to pay Stamp Duty when adding my spouse to the deeds?
You may incur a Stamp Duty bill depending on the consideration involved. HMRC defines this as any cash payment plus the share of the mortgage debt the new owner takes on. If this total exceeds the current 2026 threshold of £125,000, tax will be due. However, transfers resulting from a court order in divorce proceedings are usually exempt from these charges, regardless of the property's value or mortgage balance.
Can I perform a transfer of equity and a remortgage at the same time?
Yes, combining transfers of equity with a remortgage is a highly efficient way to restructure your finances. We handle both processes simultaneously, ensuring your new lender's requirements are met whilst the ownership change is registered. This prevents you from paying two sets of legal fees and ensures a seamless transition from your old mortgage deal to a new, more competitive interest rate that fits your updated circumstances.
Do I need to inform the Land Registry myself?
No, we take care of all Land Registry requirements on your behalf. Once the Transfer Deed is signed and witnessed, we submit the application electronically to update the Title Register. In 2026, most Land Registry applications are handled via digital portals, which reduces the risk of errors and ensures your new ownership status is recorded accurately and quickly without the need for traditional postal delays or manual paperwork.
Is a transfer of equity possible with a bridging loan?
Specialist transfers of equity are often facilitated using bridging loans to provide rapid liquidity. This is particularly useful if you need to buy out a co-owner quickly before securing a traditional long-term mortgage. We provide the expert legal oversight required for these fast-paced transactions, ensuring that the bridging finance is correctly secured against the property whilst the ownership structure is legally updated to reflect your new arrangement and financial goals.
Comments