Choosing a Buy to Let Remortgage Solicitor: The Investor’s 2026 Guide

How much is a week of legal delay actually costing your property portfolio when your current fixed rate expires? With the Bank of England base rate held at 3.75% as of June 2026, failing to switch on time can lead to a significant spike in your monthly interest payments. You likely already know that finding a specialist buy to let remortgage solicitor is vital, as general conveyancing often lacks the focus needed for complex Limited Company structures. It is a common pain point that can turn a strategic refinance into a costly administrative bottleneck.
Partnering with the right legal expert is about securing your cash flow with a team that understands the gravity of your deadlines. We will show you how to navigate the intricate lender conditions of 2026, ensuring you avoid hidden fees and maintain full compliance with the latest regulations like the Renters' Rights Act. This guide provides a methodical roadmap for choosing a legal partner who prioritises clear communication and professional efficiency, helping you move to your new rate without the stress of unexpected delays.
Table of Contents
Why Buy to Let Remortgaging Requires Specialist Legal Support
5 Key Criteria for Selecting Your Buy to Let Remortgage Solicitor
Navigating Personal vs. Limited Company Remortgage Legalities
The Legal Process: What to Expect During Your BTL Remortgage
Why Eagle Haus is the Preferred Partner for West Midlands Investors
Why Buy to Let Remortgaging Requires Specialist Legal Support
A buy to let remortgage isn't just a paperwork exercise. It's a commercial pivot that requires a specialist buy to let remortgage solicitor who understands the nuances of the 2026 market. While standard residential legal work prioritises the individual, BTL refinancing under English mortgage law treats the property as a business asset. This shift in perspective is why general conveyancers often hit roadblocks that a specialist would easily clear.
By May 2026, the Renters' Rights Act 2025 changed the fundamental structure of tenancies in England. Your solicitor must now be expert in identifying rolling periodic tenancies to ensure your lender's security isn't compromised. If your legal partner doesn't stay updated on these regulatory shifts, your entire refinancing strategy could be at risk. This level of commercial rigour is what separates a standard remortgage from a professional BTL transition.
The Complexity of BTL Lender Requirements
Lenders are becoming more protective of their capital. Most now operate via exclusive lender panels. If your chosen firm isn't on the list, you'll likely face the "double legal fee" trap where you pay for both your solicitor and the lender's representative. Beyond panel status, the legal scrutiny now extends to rental yield verification and HMO licensing. Your solicitor must act as a thorough auditor, checking that your tenancy agreements and property management standards align with the lender’s specific 2026 mandates. They'll ensure that every contract is legally sound before the lender releases any funds.
Protecting Your Investment ROI Through Speed
Time is literally money when you're refinancing. With the Bank of England base rate held at 3.75% in mid-2026, the gap between a fixed rate and a Standard Variable Rate (SVR) remains wide. A delay of just a few weeks can cost thousands in unnecessary interest. A specialist buy to let remortgage solicitor manages the "completion window" by proactively chasing documentation and ensuring the mortgage offer doesn't expire. This methodical approach keeps the momentum high and ensures you don't lose your preferred rate to administrative friction. Clear communication and a tech-savvy workflow are essential for preventing the deal from collapsing at the final stage.
5 Key Criteria for Selecting Your Buy to Let Remortgage Solicitor
Selecting a buy to let remortgage solicitor requires more than a quick search for the lowest quote. It's about finding a partner who understands the commercial pressure of a property portfolio. In 2026, the gap between a smooth refinance and a failed deal often comes down to five specific criteria. You need a team that balances technical expertise with a proactive mindset to keep your investment strategy on track.
Start by checking their ownership structure experience. Many landlords now operate through Special Purpose Vehicles (SPVs) to manage tax efficiencies. If your solicitor only handles traditional residential work, they might struggle with the added layers of company law. A solicitor's solicitor's professional duties include ensuring all parties are protected, which becomes more complex when dealing with corporate structures and personal guarantees. If you're looking for a team that balances local Staffordshire insight with national regulatory backing, consider how our remortgage services can streamline your next switch.
Lender Panel Approval: The Non-Negotiable
Lenders won't work with just any firm. If your solicitor isn't on your new lender’s approved panel, the lender will appoint their own legal representative at your expense. You'll end up paying two sets of legal fees for the same transaction. Always verify panel status before instructing. Choosing a firm with a broad reach, such as those operating via the Taylor Rose partnership, ensures you're covered for almost all major BTL lenders in the 2026 market. This avoids unnecessary costs and prevents the administrative friction that leads to delays.
Transparency in Legal Fees and Disbursements
Watch out for "teaser" quotes that look suspiciously low. These often hide essential BTL disbursements like Land Registry fees, digital AML identity checks, or additional charges for limited company work. A transparent, fixed-fee structure is vital for your cash flow forecasting. You should know exactly what you're paying from day one. This clarity allows you to calculate your property yield accurately without worrying about "hidden extras" appearing on your final completion statement. Modern firms now use digital portals to provide real-time fee breakdowns, giving you total visibility throughout the process. Don't settle for vague estimates; demand a detailed breakdown of every cost involved in your buy to let remortgage solicitor instruction.
Navigating Personal vs. Limited Company Remortgage Legalities
Choosing how to hold your property isn't just a tax decision; it's a legal one that fundamentally changes the conveyancing process. A buy to let remortgage solicitor handles a significantly higher workload when dealing with a Limited Company Special Purpose Vehicle (SPV) compared to an individual application. Whilst an individual remortgage focuses on the person, an SPV remortgage requires a deep dive into corporate structures, ensuring the company has the legal power to borrow and that all directors are fully compliant with lender mandates.
The 2026 tax landscape continues to drive investors toward corporate structures. With corporation tax rates at 19% for profits up to £50,000 and 25% for those over £250,000, the SPV remains a popular choice for higher-rate taxpayers. However, this transition brings the "Personal Guarantee" into play. Most specialist lenders require directors to be personally liable for the debt. Your solicitor plays a critical role here, often acting as a witness or providing the necessary Independent Legal Advice (ILA) to confirm you understand the gravity of the personal liability you're undertaking.
Remortgaging into a Limited Company (SPV)
Moving a property from your personal name into a company name is legally treated as a "sale and purchase" rather than a simple switch. This means your buy to let remortgage solicitor must perform full due diligence as if the company were a third-party buyer. The process requires formal corporate minutes and board resolutions to authorise the transaction. Because this "incorporation" can trigger Capital Gains Tax (CGT) at 18% or 24% and the 5% SDLT surcharge for additional properties, the legal documentation must be precise to reflect the strategic nature of the move.
Combining a Remortgage with a Transfer of Equity
Investors often need to adjust ownership shares during a refinance, perhaps to "buy out" a partner or bring a spouse onto the title for tax efficiency. We frequently manage transfers of equity alongside a remortgage to keep the process streamlined. It's a dual-layered transaction where the legal title is updated at the same time the new lender’s charge is registered. You must be mindful of Stamp Duty (SDLT) implications during this stage, as the "consideration" for the transfer usually includes the value of the mortgage debt being taken on. At Eagle Haus, we coordinate these moving parts to ensure both the new mortgage and the change in ownership complete simultaneously, preventing any gap in your legal protection.
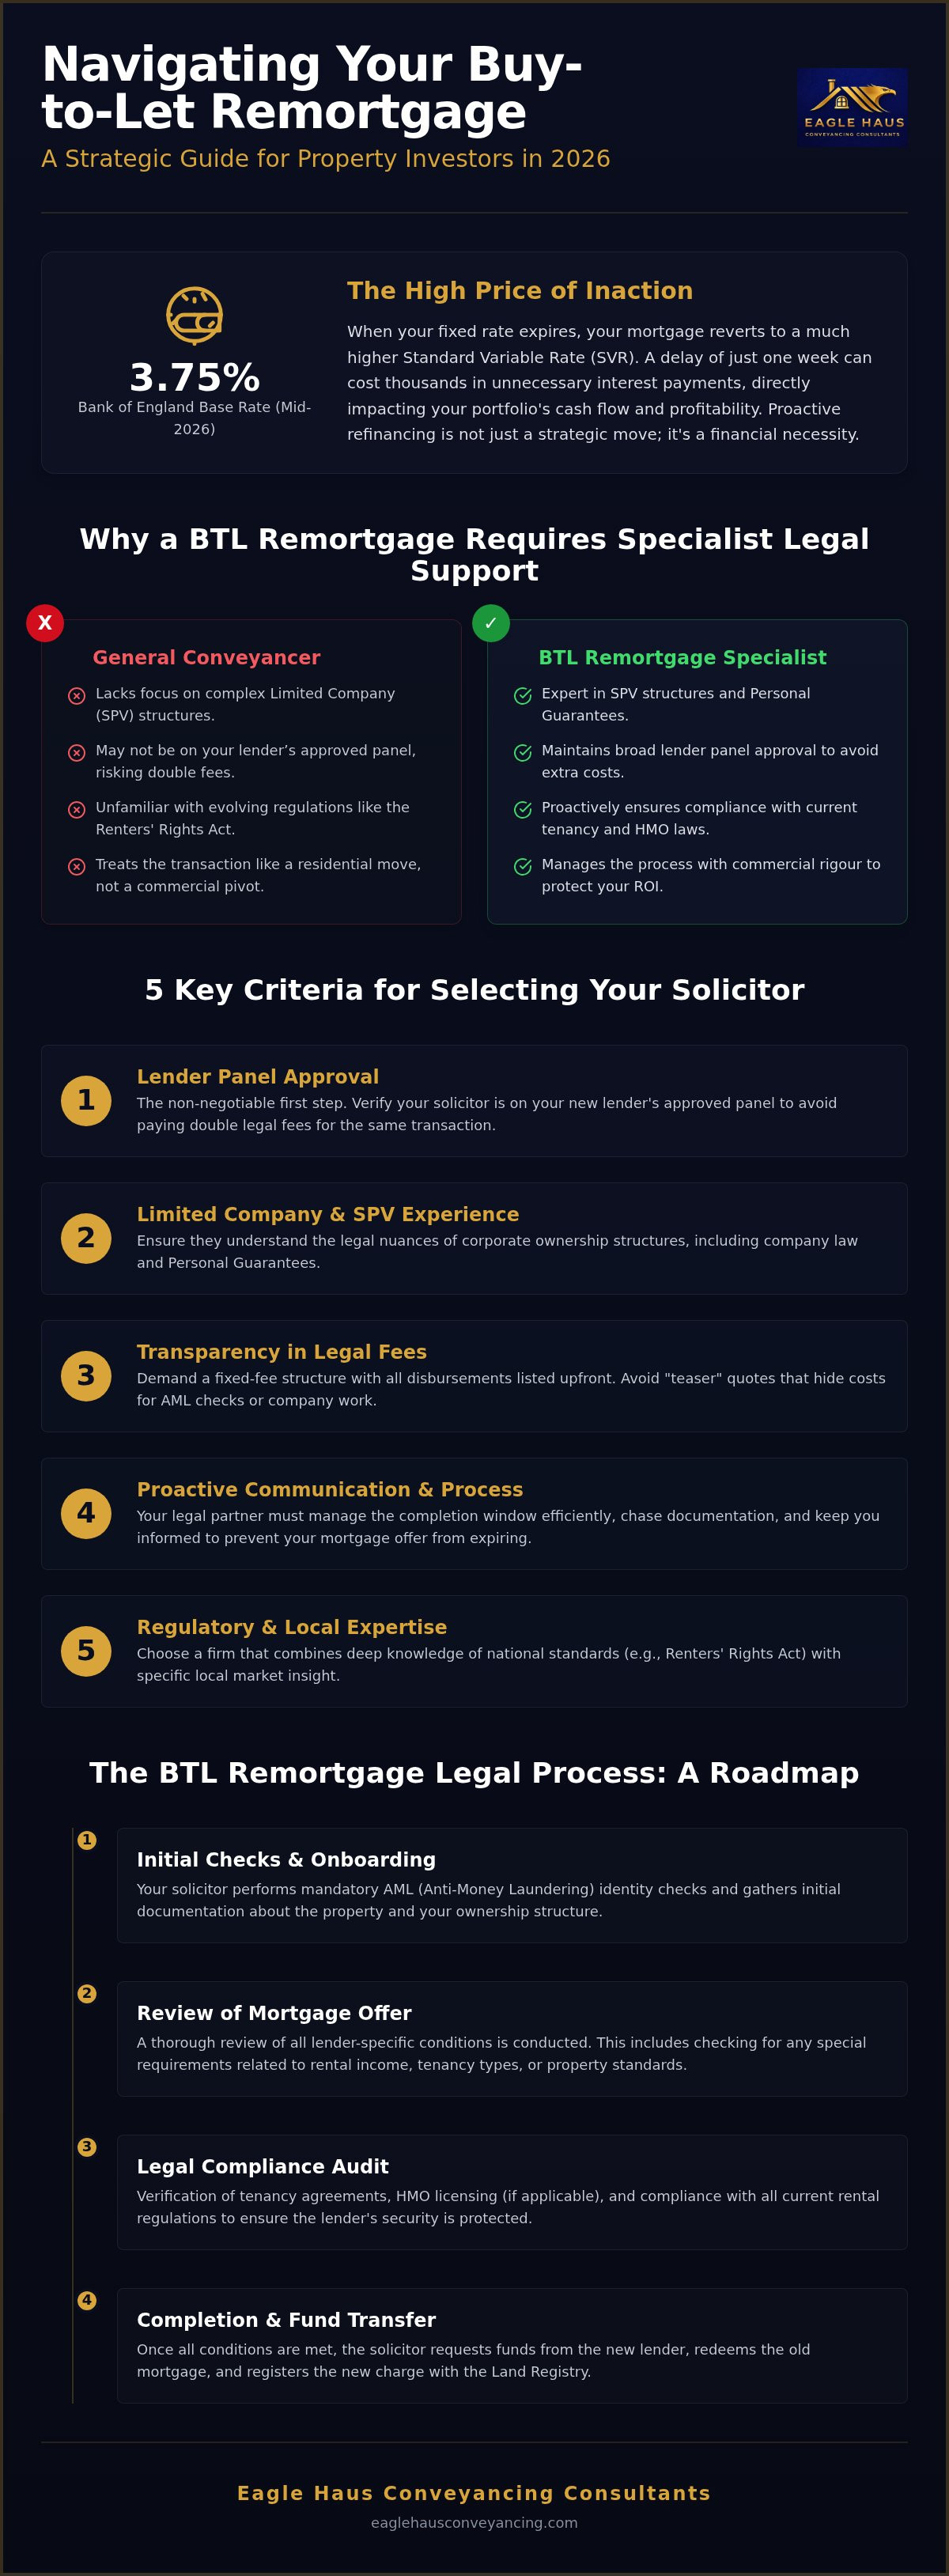
The Legal Process: What to Expect During Your BTL Remortgage
Understanding the timeline of your refinance helps you manage your portfolio's cash flow without the anxiety of the unknown. Once you instruct your buy to let remortgage solicitor, the process begins with digital Anti-Money Laundering (AML) checks. Modern firms now use biometric verification apps to speed this up, meaning you won't need to post original passports or utility bills. Following this, your solicitor will request a redemption statement from your current lender to confirm exactly how much is needed to clear the existing debt on completion day.
Your legal partner then performs a thorough title investigation. They look for restrictive covenants or secondary charges that might conflict with your new lender's requirements. This is where specialist expertise matters. A professional identifies potential issues early, ensuring they don't become deal-breakers 48 hours before completion. They also review the new mortgage offer, paying close attention to "special conditions" that are unique to professional landlords and corporate borrowers.
Document Preparation and Title Checks
You can accelerate the process by having your essential paperwork ready for review. Your solicitor will need current tenancy agreements, which must comply with the rolling periodic structures introduced by the Renters' Rights Act 2025, alongside valid Energy Performance Certificates (EPCs). For leasehold flats, they'll navigate the complexities of management packs and ground rent clauses. Under the 2026 Building Safety Act regulations, solicitors must now verify that all qualifying higher-risk buildings have a valid Building Assessment Certificate and a registered Principal Accountable Person before a new charge can be registered.
Completion and Post-Completion Tasks
Completion day is when the new lender draws down the funds to pay off your old mortgage. Your buy to let remortgage solicitor handles the electronic transfer, ensuring the old charge is discharged and your new interest rate begins immediately. This prevents you from slipping onto a costly Standard Variable Rate. After completion, they'll register the new mortgage at the Land Registry. Whilst the registration process can take several weeks to reflect on the official Title Register, your new mortgage is legally secured the moment the funds are exchanged. If you want a team that uses modern digital tools to move your refinance forward faster, you can start your remortgage instruction today.
Why Eagle Haus is the Preferred Partner for West Midlands Investors
Investors in the West Midlands require more than just a legal service; they need a strategic partner who understands the local landscape. Whether you are managing a portfolio in Birmingham or growing your assets in the Staffordshire market, having a dedicated buy to let remortgage solicitor makes a measurable difference to your completion speed. We bridge the gap between boutique, personal attention and the robust regulatory backing of a national firm. By providing our services via the Taylor Rose partnership, we offer the peace of mind that comes with high-tier professional indemnity and a seat on almost every major BTL lender panel in 2026.
Our approach is built on being a modern professional guide. We don't believe in the distant, formal style of traditional law firms. Instead, we prioritise proactive communication and transparency. If you are dealing with complex bridging loans or moving assets into a Limited Company SPV, our specialists handle the technical heavy lifting so you can focus on your investment strategy. We understand the pressure of the current 3.75% base rate environment and the importance of switching before your offer expires. This expertise ensures your transaction is handled with the commercial rigour it deserves.
Boutique Service, National Reach
We pride ourselves on providing a tailored experience for landlords in Staffordshire, Wolverhampton, and Telford. You won't be passed between anonymous departments. Instead, you'll work with a local consultant who understands the nuances of the West Midlands property market. Whilst we offer a personal touch, we use modern technology to accelerate your conveyancing journey. Our digital ID checks and online document portals mean you can progress your remortgage from anywhere, avoiding the need for time-consuming office visits or postal delays. This combination of local insight and digital efficiency is why we remain the first choice for professional investors.
Taking the Next Step with Eagle Haus
Ready to secure your next rate? The first step is requesting a transparent, itemised quote. We don't use "teaser" prices that hide essential disbursements. Your quote will clearly outline the legal fees and the specific costs associated with BTL work, such as company minutes or personal guarantee witnessing. Once you're ready to proceed, our buy to let remortgage solicitor will conduct an initial consultation and document review to identify any potential hurdles before they cause a delay. This methodical start ensures a smooth transition to your new mortgage product. You can Secure your next BTL deal with Eagle Haus and experience a more efficient way to manage your property legalities.
Secure Your Portfolio’s Growth in 2026
Navigating the 2026 buy to let market requires more than a standard conveyancing service. It demands a legal partner who understands the commercial pressure of property investment. By prioritising specialist expertise in Limited Company SPV structures and ensuring your buy to let remortgage solicitor sits on the correct lender panels, you protect your cash flow from the risks of administrative delay and high revert-to-rates. We have explored how a methodical approach to title checks and proactive communication can turn a complex refinance into a smooth, predictable transition.
At Eagle Haus, we offer the perfect balance of deep local knowledge in Birmingham and Staffordshire with the national regulatory strength of our SRA-regulated partnership with Taylor Rose. We're here to help you manage the technicalities of personal guarantees and ownership transfers with total clarity. If you're ready to move your investment forward with a modern, tech-savvy team, you can Request a Fixed-Fee BTL Remortgage Quote from Eagle Haus today. Your next strategic refinance doesn't have to be a source of stress. With the right guide, it's a clear step toward a more secure financial future.
Frequently Asked Questions
Do I really need a solicitor to remortgage a buy to let property?
Yes, you must instruct a solicitor because a remortgage involves changing the legal charge registered against your property title. A legal professional is required to discharge the existing mortgage, verify the new lender's security, and update the Land Registry records. This process ensures the new lender has a valid first charge and that your legal ownership remains protected throughout the transition.
How long does the legal process take for a BTL remortgage in 2026?
The legal process typically takes between four and eight weeks from the moment your solicitor receives the mortgage offer. Whilst digital identity checks and online portals have accelerated the initial stages, the timeline depends on the speed of your current lender providing a redemption statement. Complexities such as leasehold management packs or multi-unit blocks can also extend the completion window.
What are the typical solicitor fees for a buy to let remortgage?
Fees vary based on whether you're borrowing personally or through a Limited Company structure. An SPV remortgage generally carries a higher cost due to the additional corporate due diligence and the requirement for board resolutions. You should always look for a fixed-fee quote that includes a clear breakdown of disbursements, such as Land Registry fees and digital AML search costs, to maintain accurate yield forecasts.
Can I use the same solicitor for a remortgage and a transfer of equity?
Yes, and it's often the most efficient way to manage your portfolio. Your solicitor can coordinate the update to the legal title, such as adding a spouse or buying out a partner, at the same time as the refinance. This dual-process approach ensures that the new mortgage charge and the change in ownership are registered simultaneously, preventing any gap in your legal standing or lender compliance.
What is an SPV and does it require a different type of solicitor?
An SPV is a Limited Company set up specifically for property investment, and it definitely requires a specialist buy to let remortgage solicitor. Unlike personal applications, an SPV remortgage involves a review of the company's articles of association and the provision of personal guarantees. A solicitor with corporate expertise ensures that the company is authorised to borrow and that all director obligations are legally met.
What happens if my solicitor isn’t on my lender’s approved panel?
The lender will appoint their own legal representative to act for them, and you'll be required to pay their fees in addition to your own solicitor's costs. This "double legal fee" trap can significantly increase your refinancing expenses. Always confirm that your chosen firm has panel approval for your specific lender before you provide formal instructions to avoid unnecessary financial friction.
Do I need to visit the solicitor’s office in Staffordshire or Birmingham in person?
No, there's no requirement for a physical visit in the modern legal landscape. Whilst we have deep roots in the West Midlands and Staffordshire property markets, our workflow is entirely digital. You can complete identity checks via biometric apps and sign most documents electronically. This tech-savvy approach allows you to manage your portfolio's legal needs from anywhere without the need for time-consuming travel.
What documents should I prepare before instructing a remortgage solicitor?
Gather your current tenancy agreements, valid Energy Performance Certificates (EPCs), and your latest mortgage statement. If you're remortgaging as a company, ensure your SPV’s registration documents and director details are current. Providing these to your buy to let remortgage solicitor at the start of the process prevents delays and allows for an immediate start on the necessary title investigations and AML checks.
Comments