How to Compare Remortgage Conveyancing Quotes: A 2026 Homeowner’s Guide

That "free legal" incentive from your new lender might actually be the most expensive mistake you make this year. When you start comparing remortgage conveyancing quotes, it's tempting to focus solely on the headline figure, but the cheapest price often hides a labyrinth of disbursements and supplemental fees. You need a transition that's smooth and predictable, not a legal process that stalls whilst your mortgage offer ticks toward expiry.
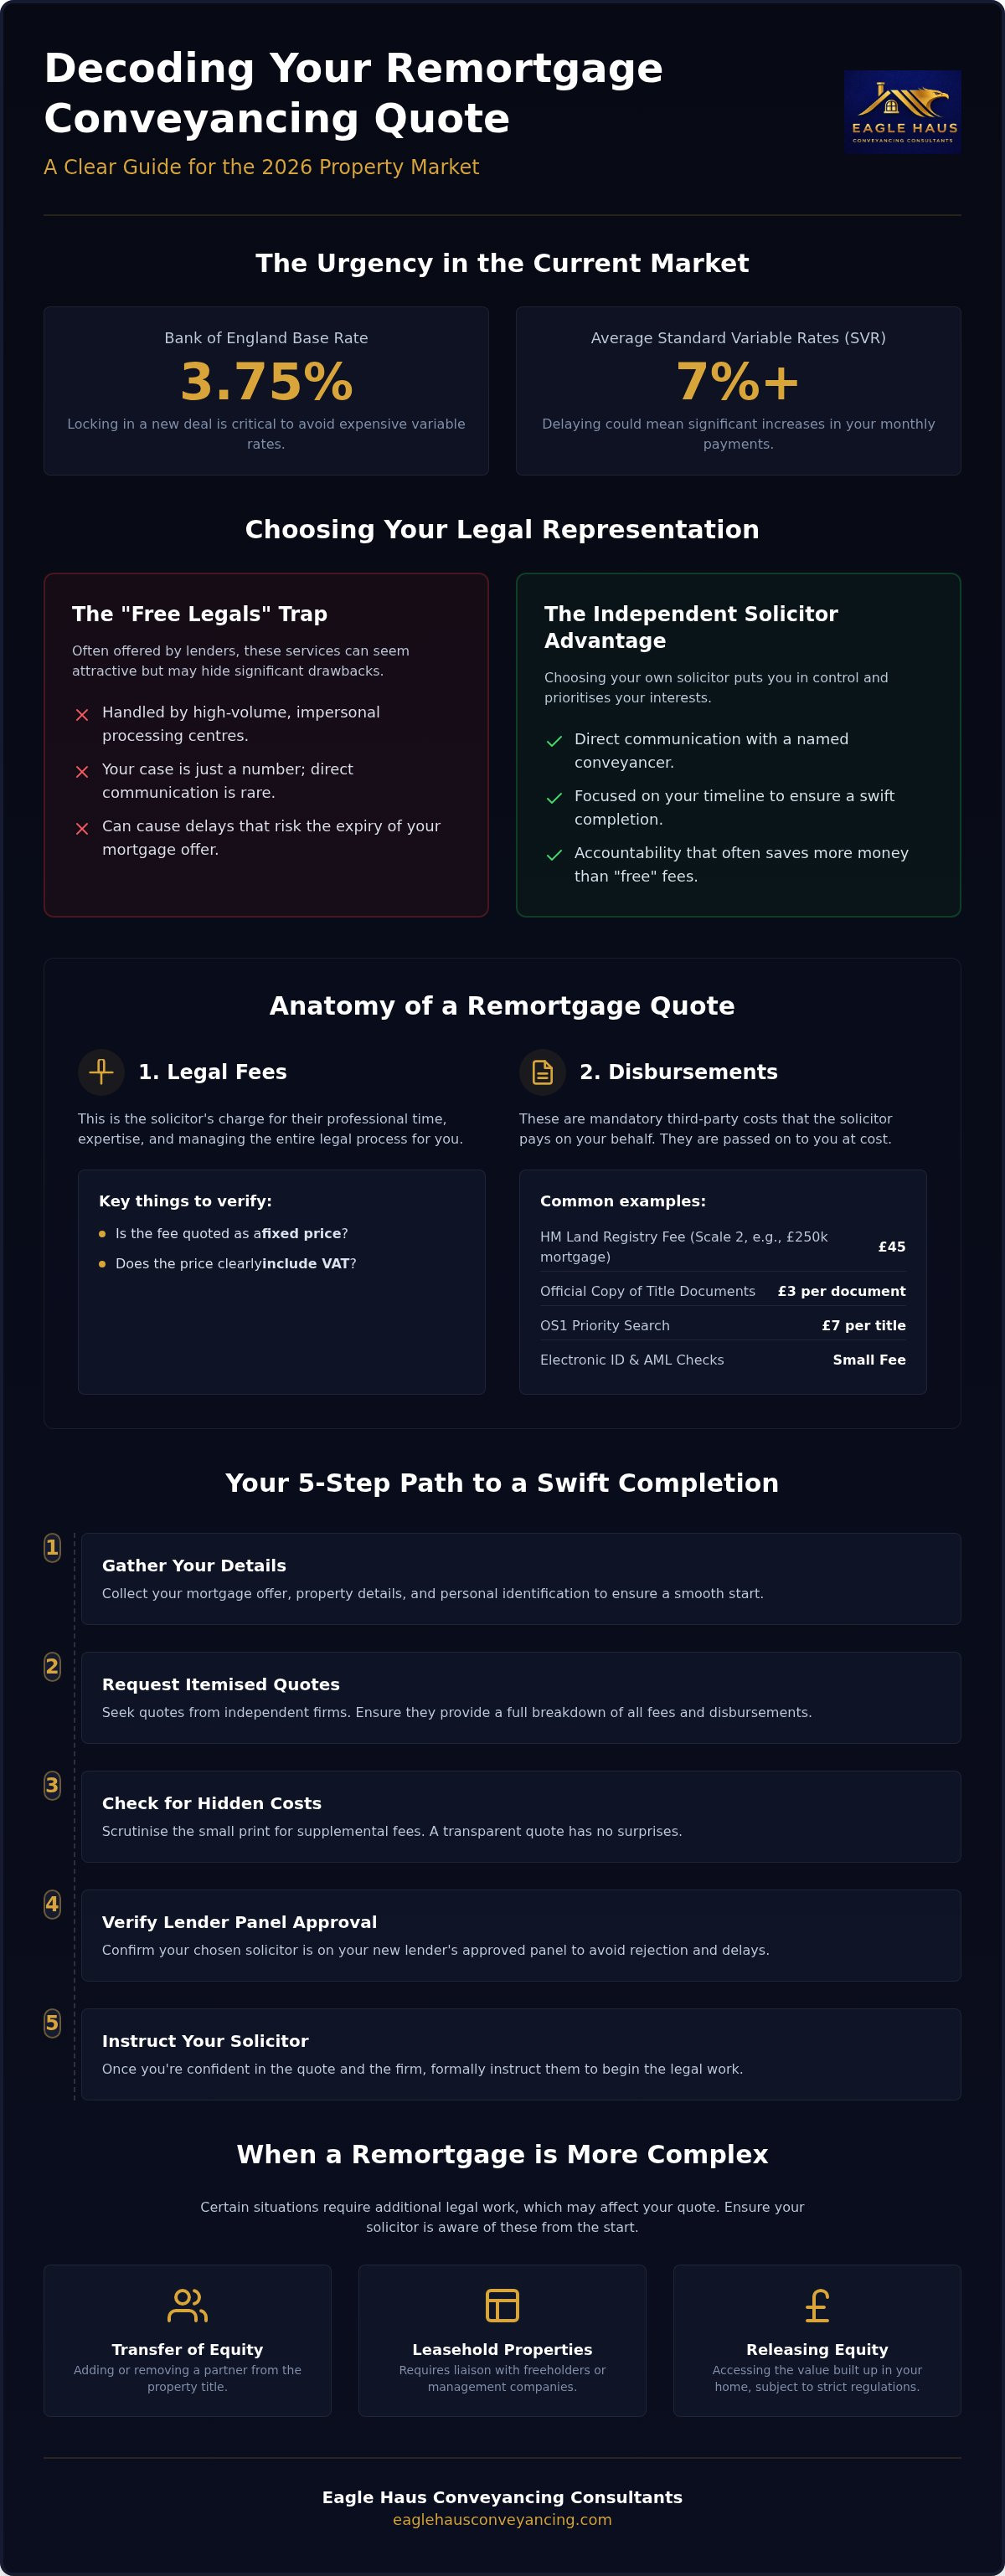
We understand the pressure of the 2026 market. With the Bank of England base rate at 3.75% and average Standard Variable Rates climbing over 7%, the urgency to lock in a new deal is real. You're likely worried about hidden costs or the fear of your chosen solicitor being rejected by your lender's panel. It's a stressful position to be in when you're simply trying to protect your monthly budget.
This guide will teach you exactly how to decode a legal quote, avoid the traps of "extra" charges, and ensure your solicitor is ready to move. We'll provide a clear roadmap to finding a transparent, fixed-fee partner, helping you achieve a swift completion before the next rate hike changes the landscape again.
Table of Contents
Understanding Remortgage Conveyancing Quotes in 2026
When you look at remortgage conveyancing quotes, you're essentially paying for the legal bridge between your old lender and your new one. While many homeowners assume that what conveyancing is only applies to buying or selling, the legal work required for a remortgage is just as vital. The solicitor's primary role is to redeem your existing mortgage, verify the title deeds, and register the new lender's legal charge with HM Land Registry. Even though you aren't moving house, the debt's legal ownership is shifting. This requires a formal framework to protect your equity and ensure the new lender has the correct security over the property.
The 2026 property market is moving fast. With the Bank of England base rate holding at 3.75% as of July 2026 and Standard Variable Rates (SVR) climbing above 7%, homeowners are increasingly motivated to switch deals quickly. This surge in activity means that the structure of a quote isn't just about the price; it's about the capacity of the firm to handle the work before your current offer expires. A quote should clearly outline how the solicitor will manage the transition, ensuring no gap exists where you are left on an expensive SVR.
Why Independent Quotes Often Beat 'Free Legals'
Lenders frequently offer "free legal" packages as an incentive to switch. Whilst this sounds attractive, these services are often outsourced to high-volume processing centres where you are simply a case number in a vast system. Choosing an independent solicitor allows you to prioritise your own timeline. Independent firms focus on your specific interests rather than the lender's volume targets. You'll typically benefit from direct communication with a named conveyancer, which is essential if your case encounters a hurdle. In a market where mortgage deals can be pulled or repriced overnight, the speed and accountability of an independent firm often save you more in interest than the "free" service saves you in fees.
When a Remortgage Becomes More Complex
Standard remortgages are relatively linear, but certain property types or life changes add layers of complexity. If you're using the opportunity to add or remove a partner from the property title, your solicitor will need to perform a transfer of equity alongside the new loan. Leasehold properties also require more intensive work, as the solicitor must review the lease terms and liaise with the freeholder or management company. For homeowners looking to access the value built up in their property, instructing a solicitor for remortgage to release equity ensures that the strict regulatory requirements are met without delaying the arrival of your funds.
Breaking Down the Costs: Legal Fees vs Disbursements
Navigating remortgage conveyancing quotes requires a clear understanding of where your money goes. Every quote is divided into two primary categories: legal fees and disbursements. Legal fees are the professional charges for your solicitor’s time and expertise in managing the legal transition. It's essential to check that these fees are quoted as fixed and include VAT from the outset. Some firms might headline a low price only to add VAT later, making a significant difference to your final balance when you're trying to budget for your new mortgage deal.
Clarity on third-party costs is equally important. Disbursements are mandatory costs paid to external bodies like the Land Registry. These aren't set by your solicitor; they're simply passed through to you at cost. For homeowners navigating specific schemes or borrowing more against their property, checking official remortgage guidance can provide insight into the extra layers of administration that might influence your total bill.
Common Remortgage Disbursements in 2026
For a typical 2026 remortgage, your disbursements will include Scale 2 Land Registry fees. For a new mortgage of £250,000, this is currently £45 for an electronic application. You'll also pay for official copies of your title documents, which cost £3 per document, and an OS1 priority search at £7 per title. Modern security is non-negotiable, so expect a small fee for electronic ID verification (AML checks). These digital tools ensure your identity is verified quickly and securely, preventing fraud and keeping the instruction phase moving forward without the need for physical paperwork.
Lender-Specific Requirements and Admin Fees
Lenders frequently impose their own administrative costs that your solicitor must manage on your behalf. The most common is the telegraphic transfer (CHAPS) fee, typically around £30 including VAT, which covers the secure transfer of funds to redeem your existing mortgage. You may also see a lender portal management fee on your quote. This covers the cost of using the bank's secure digital platform to exchange documents and updates. If speed is your priority, your lender might suggest 'no-search' indemnity insurance. This policy protects the lender against issues a local search would have revealed, allowing the legal process to skip lengthy council waiting times. If you want to see how these costs apply to your specific situation, you can get a tailored fee estimate from our team of specialists.
How to Compare Quotes Without Falling for Hidden Fees
Comparing remortgage conveyancing quotes requires a sharp eye for what isn't on the page. A low headline price is often used as a hook to attract interest, but the final bill can look very different once supplementary costs are added. Transparency in remortgage legal fees is the most reliable indicator of a firm's service quality. A reputable solicitor will provide an itemised breakdown from the start, ensuring you aren't surprised by "extra" charges for tasks that should be part of the standard process.
When you review a guide to remortgaging, you'll see that efficiency is just as important as price. A cheap quote from a firm that lacks the technology to move quickly could cost you thousands if your mortgage offer expires before completion. You should look for a firm that balances a competitive fee with a modern, tech-led approach, ensuring your transition to a new lender happens before the next interest rate shift.
The Lender Panel Red Flag
The most critical detail to check is the "Lender Approved Panel" status. Every bank has a list of solicitors they trust to act for them. If your chosen firm isn't on your new lender's approved list, the bank will appoint their own solicitor to act for them. This leads to "split representation," and you'll likely be billed for both sets of legal fees. It's a costly oversight. Always ask a firm if they can act for your specific lender, especially if you're using a niche or specialist provider. A firm that is part of a larger network, like Taylor Rose, typically has the national regulatory strength to act for almost every UK lender.
Spotting the 'Hidden' Extras
Beyond the professional fee, look closely at the small print for administrative extras. Some high-volume firms add archive fees, postage charges, or "file opening" fees that aren't included in the headline remortgage conveyancing quotes. These small costs quickly add up. You should also check for supplements related to your specific property type. Leasehold properties often attract a higher fee because the solicitor must review the lease and liaise with the freeholder. Similarly, if your remortgage involves a gifted deposit or a second charge on the title, expect a modest additional fee for the extra legal work required. Finally, be wary of "No Completion, No Fee" promises. Read the terms to see if you're still liable for disbursements already paid, such as Land Registry searches, even if the remortgage doesn't go through.
The 5-Step Process to Securing and Instructing Your Quote
Securing the right legal support shouldn't be a reactive process. Many homeowners make the mistake of waiting until their mortgage offer arrives before they begin looking at remortgage conveyancing quotes. In the 2026 market, where interest rates can fluctuate rapidly, this delay often leads to a frantic rush. By following a structured approach, you can ensure your legal paperwork is ready the moment your lender gives the green light. Leading with a proactive mindset prevents the stress of a looming expiry date on your mortgage offer.
Step 1: Gather your property details. You'll need your current mortgage balance, an estimated property value, and your title number if you have it.
Step 2: Request an itemised quote. Look for a firm that provides a transparent breakdown of both legal fees and disbursements.
Step 3: Verify lender panel status. Confirmation that the firm can act for your specific bank is essential to avoid double-charging or delays.
Step 4: Instruct your solicitor early. Start the "starter pack" and ID checks immediately. This allows your solicitor to request your current title deeds and redemption statement whilst your mortgage application is being processed.
Step 5: Review and sign. Once the mortgage offer is issued and the title is checked, you'll sign the new mortgage deed to facilitate the transfer of funds.
Information You Need for an Accurate Quote
To get a quote that won't change later, you must provide specific details about your situation. This includes whether your property is freehold or leasehold and if you intend to change who is named on the title. If you are an investor, you should specifically seek a buy to let remortgage solicitor. These transactions often involve more complex lender requirements, such as verifying tenancy agreements or checking for specific portfolio restrictions. Having this information ready ensures your solicitor can account for the extra legal work from the outset.
What Happens After You Accept the Quote?
Once you've accepted a quote, the onboarding process begins. Modern firms use digital ID checks and secure portals to handle your "source of funds" verification. This is far more efficient than the traditional method of posting physical documents. Your solicitor will also liaise directly with your mortgage broker to ensure they have the most up-to-date information on your application. This partnership is vital for setting a realistic completion date that aligns with your current deal's expiry. If you're ready to start the process now, you can request your fixed-fee remortgage quote and secure your place in our completion schedule.
Why Local Expertise Matters for Your Remortgage in the West Midlands
Whilst national comparison sites often treat all remortgage conveyancing quotes as equal, they frequently overlook the nuances of the West Midlands property market. The legal process for a remortgage is standard, but the property itself is tied to its location. Whether your home sits above historical mining works in Staffordshire or involves complex leasehold structures in Birmingham city centre, local knowledge prevents unnecessary delays. A solicitor who understands regional title issues can anticipate the specific searches or indemnity policies a lender might require, ensuring your application doesn't stall at the final hurdle.
Eagle Haus provides a boutique service that prioritises personal connection. We combine this approachable, human-led style with the national regulatory strength of our partnership with Taylor Rose. This gives you the best of both worlds: the attention of a specialist firm and the assurance that we are on the approved panel for almost every UK lender. You won't be passed between anonymous departments; you'll have access to professionals who understand the landscape in Wolverhampton, Telford, and the surrounding areas.
Serving Staffordshire, Birmingham, and Beyond
Our commitment to the region extends across Cannock, Walsall, and Shropshire. We recognise that the West Midlands is a hub for property investment, and we frequently handle complex remortgages for local landlords. These investors often face tighter deadlines and more rigorous lender requirements. Our approach is modern and tech-savvy, using digital portals to speed up ID checks and document sharing, but it remains fundamentally local. We know that being able to speak to a real person who understands your specific street or development provides a level of reassurance that automated platforms simply cannot match.
Your Next Steps for a Stress-Free Remortgage
Getting a bespoke quote shouldn't be a complicated or opaque process. We believe in fixed-fee transparency, ensuring that the price you are quoted is the price you pay. This clarity allows you to budget effectively for your new mortgage deal without the fear of "supplementary" legal costs appearing on your final completion statement. In a market where the Bank of England base rate remains a key focus for homeowners, a swift and predictable legal transition is your best defence against rising costs. If you're ready to move forward with a team that values your time and your peace of mind, you can get your transparent remortgage conveyancing quote from Eagle Haus today.
Secure Your Fixed-Fee Remortgage Today
Remortgaging in 2026 requires more than just finding a low interest rate; it demands a legal partner who prioritises speed and transparency. By scrutinising remortgage conveyancing quotes for hidden disbursements and verifying lender panel status early, you protect yourself from unexpected costs and avoidable delays. Whether you're navigating a leasehold in Birmingham or a complex title in Staffordshire, the right solicitor acts as your guide through the digital onboarding process.
At Eagle Haus, we combine modern, tech-savvy efficiency with a deeply human approach. As specialists in West Midlands property law regulated through Taylor Rose, we provide the national strength you need with the boutique service you deserve. Our fixed-fee guarantee means you won't face surprise charges, letting you focus on the savings your new mortgage deal provides. Don't let legal hurdles slow down your transition to a better rate.
Get your transparent, fixed-fee remortgage conveyancing quote from Eagle Haus and take the first step toward a stress-free completion. We're ready to help you secure your financial future with confidence.
Frequently Asked Questions
How much should remortgage conveyancing quotes actually be in 2026?
In 2026, typical legal fees for a remortgage range between £200 and £450 plus VAT, although some specialised cases may reach £550 including VAT. These figures represent the professional fee for the solicitor's time and expertise. You must also account for disbursements, such as Land Registry fees and search costs. Comparing remortgage conveyancing quotes helps you identify which firms offer a transparent fixed-fee approach versus those with hidden extras.
Do I need a solicitor if I am staying with the same mortgage lender?
You generally don't need a solicitor if you are simply switching to a new deal with your existing lender, a process known as a product transfer. Since the legal charge on the property remains with the same institution, no new conveyancing is required. However, if you intend to borrow more money or change the names on the title deeds, you'll need legal support to update the Land Registry records and manage the additional funds.
Can I use the same solicitor who handled my original house purchase?
You can use the same solicitor who handled your purchase, provided they are on your new lender's approved panel. Using a firm that already has your property history can sometimes streamline the initial document gathering phase. It's still wise to request a fresh quote to ensure their current fees are competitive. Always check that they've updated their systems to handle the digital requirements of the 2026 mortgage market.
What happens if my remortgage solicitor isn't on my lender's panel?
If your solicitor isn't on the lender's panel, the bank will appoint their own legal representative to protect their interests. This usually results in split representation, where you are responsible for paying two sets of legal fees. It often causes significant delays as documents are passed between two different firms. To avoid this, verify your solicitor's panel status before instructing them to ensure a direct and cost-effective transition.
How long does the legal process take for a standard remortgage?
A standard remortgage typically takes between four and eight weeks to complete from the moment you instruct your solicitor. This timeline depends on how quickly your lender issues the formal offer and how fast your current lender provides a redemption statement. Using a firm with modern digital onboarding tools can shave days off this process by completing ID checks and document signing through secure online portals.
Is a transfer of equity included in a standard remortgage quote?
A transfer of equity is not included in a standard quote and will attract an additional professional fee. This process involves legally changing the ownership structure of the property, such as adding or removing a partner. Because it requires extra work to draft the transfer deed and verify the new owner's identity, solicitors treat it as a separate legal instruction that runs alongside your remortgage.
What are the most common hidden fees in conveyancing quotes?
The most common hidden extras include archive storage fees, postage and petty charges, and separate fees for acting for the lender. Some firms also charge additional sums for redeeming a second charge or handling a Help to Buy loan. Always look for a fixed-fee guarantee that explicitly includes these administrative tasks. Transparency at the quote stage is the best way to ensure your final bill matches your expectations.
Can I get a remortgage quote for a property owned by a limited company?
You can obtain a quote for a limited company remortgage, but expect to pay a supplement for the additional complexity involved. In 2026, many firms charge an extra fee of around £275 including VAT for company cases. This covers the extra work required to check Company House records, verify corporate structures, and ensure the mortgage deed is executed correctly according to the company's articles of association.
Comments