Shared Ownership Houses: The 2026 Guide to Part-Buy, Part-Rent Success

If you're tired of watching house prices outpace your savings, the reality of owning one of the many shared ownership houses across the West Midlands might be closer than you think. With the 2026 model now offering initial shares from as low as 10%, the barrier to entry has never been more accessible. It's completely natural to feel overwhelmed by the jargon of leaseholds, staircasing, and service charges. You want a home that offers stability, not a mountain of hidden legal paperwork and unexpected costs.
This guide will demystify the shared ownership scheme, showing you how to navigate the legal process and secure your future with total confidence. We'll break down the true costs of the 2026 regulations, explain your path to 100% ownership, and help you find a conveyancer who understands the local markets in Telford, Birmingham, and Cannock. By the end, you'll have a clear, step-by-step roadmap to move from renter to homeowner without the stress of the traditional open market.
Table of Contents
Understanding Shared Ownership Houses in the 2026 Property Market
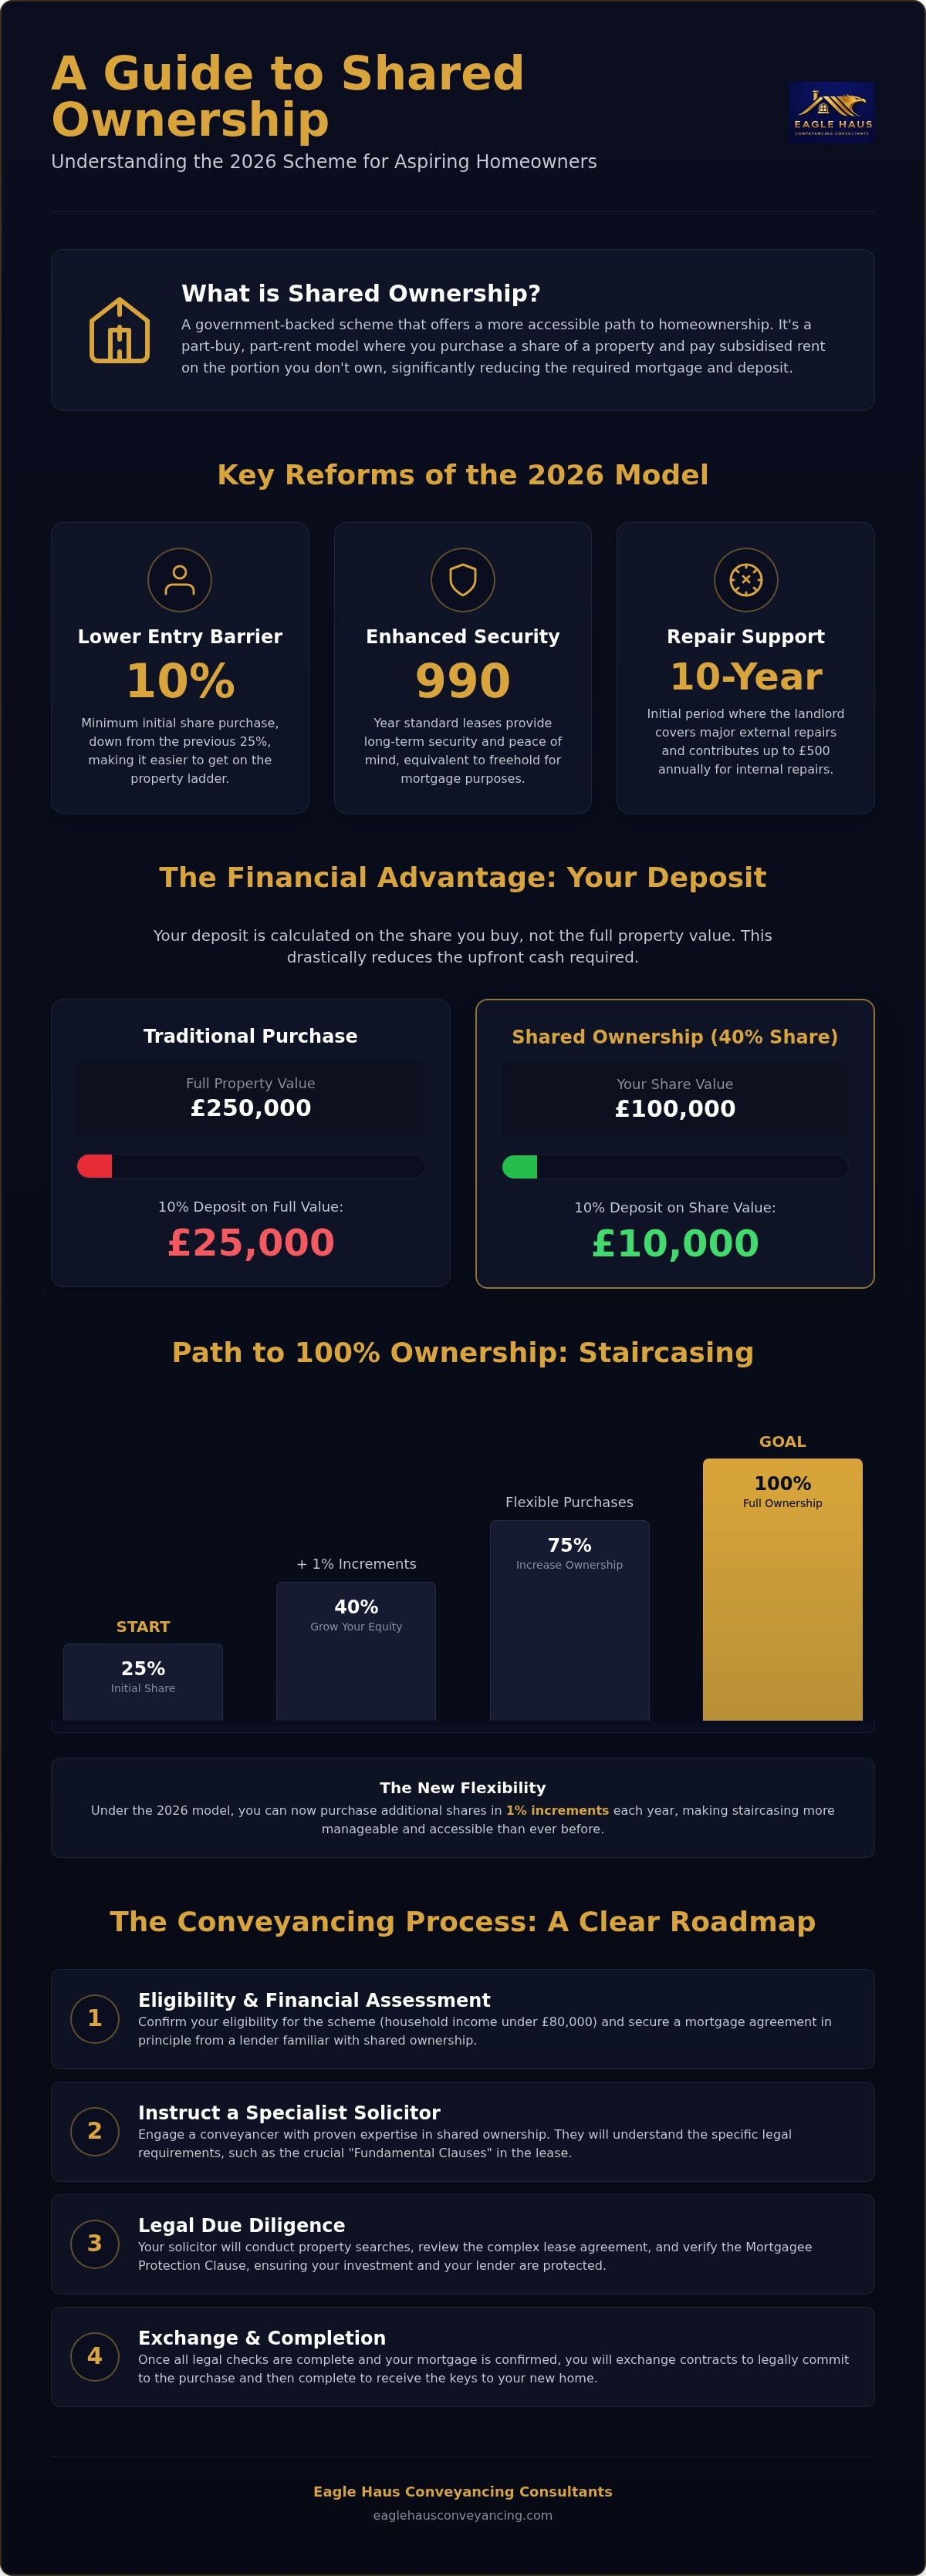
Shared ownership is a government-backed initiative designed to help you step onto the property ladder when the open market feels out of reach. At its heart, the scheme is a form of shared ownership or co-ownership where you buy a percentage of a property and pay a subsidised rent on the remaining portion. This approach significantly reduces the size of the mortgage you need, making the dream of a permanent home a practical reality.
The 2026 property market has seen a shift in how these schemes operate. Under the current Affordable Homes Programme, the entry point for shared ownership houses has become even more accessible. You can now purchase an initial share as low as 10%, compared to the 25% minimum required in previous years. This change is specifically designed to support buyers in areas where house prices have risen sharply, ensuring that ownership remains a viable option for local families.
In the West Midlands and Staffordshire, there's a clear trend of buyers moving away from urban apartments in favour of houses. Whether it's the need for a garden in Cannock or extra space for a home office in Telford, shared ownership houses provide the longevity that flats often lack. Your partner in this journey is typically a Housing Association. They act as your landlord for the share you don't own, but they also serve as a professional partner committed to maintaining the quality of the development.
The Core Mechanics of Part-Buy, Part-Rent
Success in this scheme relies on balancing two monthly payments: your mortgage and your rent. Because you're only borrowing for a fraction of the property's value, your deposit is calculated on that share, not the full price. You'll need to understand that these homes are sold on a leasehold basis. Modern 2026 leases are now standard at 990 years, giving you long-term security. To ensure you're fully protected, it's vital to learn how does shared ownership work from a legal perspective, especially regarding the landlord's obligations for repairs during the first ten years.
Who is Shared Ownership For?
This path is primarily built for households with an annual income of less than £80,000 outside of London. It's a popular choice for first-time buyers in Wolverhampton and Walsall who have steady incomes but haven't yet amassed a massive deposit. While the "First Homes" scheme offers a fixed discount on the purchase price, shared ownership provides more flexibility through the ability to buy more of the property over time. This makes it a proactive choice for those who want their home to grow alongside their financial situation.
The Legal Framework: How Shared Ownership Leases Operate
When you purchase one of the many shared ownership houses available today, you're entering into a unique legal contract. Unlike traditional house purchases where you usually own the land and building outright, these properties are almost always sold as leaseholds. This structure allows the Housing Association to retain the share you haven't yet purchased whilst granting you the right to live there for a very long term. To understand the broader rules, you can consult the official government guide, but the day-to-day legal reality is governed by specific "Fundamental Clauses" within your lease.
These clauses are non-negotiable. Lenders require them to approve a mortgage because they provide a safety net for the bank. One critical element is the Mortgagee Protection Clause. This protects your lender if you default on your payments, making shared ownership a viable risk for banks and building societies. Without these protections, securing a mortgage on a part-owned property would be incredibly difficult for most buyers.
You'll also need to be clear on maintenance. Historically, shared owners were responsible for 100% of repair costs from day one. However, for homes under the current 2021-2026 programme, a new 10-year initial repair period applies. During this time, the landlord is responsible for the cost of major repairs to the external fabric of the building. You can also claim up to £500 annually from the landlord for essential internal repairs. Outside of this period, or for older resale properties, the full responsibility for maintenance falls on you, regardless of the size of your share.
Leasehold vs. Freehold in Shared Ownership
In the standard UK market, most houses are freehold. Within this scheme, they remain leasehold to facilitate the part-buy, part-rent model. The modern standard for these leases is now 990 years, providing significant long-term security. Once you "staircase" to 100% ownership, you typically have the right to acquire the freehold, effectively turning the property into a traditional home. If you're unsure how this transition works for a specific property, getting expert residential conveyancing advice early on can prevent surprises later.
The Landlord-Tenant Relationship
Living in a shared ownership house feels like being an owner-occupier, but legally, you're a tenant with a very long lease. This means you must follow certain rules. For example, subletting your entire home is generally prohibited until you own 100%. Similarly, structural alterations like adding an extension or a conservatory usually require written consent from the Housing Association. They also manage communal maintenance in new estates, such as landscaping or shared driveways, which is funded through your monthly service charge.
Eligibility and Financial Reality in the West Midlands
In Wolverhampton and Walsall, local councils often prioritise applicants who already live or work in the area. This local connection can be a deciding factor when several people apply for the same shared ownership houses. While the national income threshold is £80,000, local authorities might set lower limits for specific developments to ensure they remain truly affordable for the local community. It's a proactive way to help residents stay in their own neighbourhoods whilst moving from renting to owning.
The most significant financial benefit of the scheme is the deposit. Instead of needing 5% or 10% of the property's total market value, you only need that percentage of the share you're actually buying. If you're purchasing a 25% share of a £200,000 house, your 5% deposit is calculated on £50,000, not the full amount. This makes the initial cash requirement much more manageable. According to official government guidance on shared ownership, these financial benefits are a cornerstone of the scheme's accessibility for first-time buyers.
Beyond the deposit, you'll need to budget for several initial costs. These include a reservation fee, which usually ranges from £250 to £500, and valuation fees. Legal costs also differ slightly because the conveyancing involves more complex lease reviews. When comparing shared ownership conveyancing fees to standard purchases, you'll notice they are often slightly higher to reflect the extra work required to liaise with the Housing Association and verify the specific lease terms.
Affordability Checks in Staffordshire and Shropshire
Before you can proceed, an Independent Financial Advisor (IFA) must conduct a thorough assessment. They don't just look at your mortgage; they calculate your total debt-to-income ratio, including the rent and service charges you'll pay on the unowned share. In Birmingham and Telford, where living costs vary, this check ensures you aren't overextending yourself. The goal is to prove that your total housing costs are sustainable for the long term, giving both you and the landlord peace of mind.
Service Charges and Sinking Funds
Even if you live in a house rather than a flat, you'll likely pay a service charge. This covers the maintenance of communal areas, estate lighting, and building insurance. A portion of this often goes into a "sinking fund." This is a collective pot of money reserved for major future repairs, such as resurfacing a shared driveway or replacing fencing. It's a reassuring safety net that prevents you from being hit with a massive, unexpected bill. If you feel an increase in these charges is unfair, you have the legal right to request a breakdown of the costs or challenge them through a tribunal.
The Shared Ownership Conveyancing Process: Step-by-Step
The legal journey for shared ownership houses begins the moment your application is approved and the Housing Association issues a "Memorandum of Sale." This document summarises the agreed price, the share you're purchasing, and the contact details for all solicitors involved. It's the official starting gun for the legal work. At this stage, it's essential to instruct a solicitor who truly understands how does shared ownership work from a technical standpoint. Unlike a standard purchase, your legal representative must review the "Fundamental Clauses" required by Homes England to ensure the lease is compliant and mortgageable.
Your solicitor will carry out an intensive lease review, looking specifically at staircasing terms and any restrictive covenants that might limit how you use your home. Some leases have "Designated Protected Area" status, which might restrict you from ever owning 100% of the property. Catching these details early is what prevents delays or future financial headaches. They'll also check the landlord’s nomination period, which dictates how you can sell the property in the future.
The Legal Search Phase
Your solicitor will order a suite of searches to uncover any issues with the land or local area. In regions like Cannock and across Staffordshire, local authority searches are vital to check for planned developments or road changes nearby. For new-build sites, environmental and drainage searches are equally critical to ensure the infrastructure is sound. These searches often take slightly longer for shared ownership developments because the sites are frequently part of larger, multi-phase regeneration projects with complex planning histories.
Mortgage Offer and Lease Approval
Once your mortgage offer arrives, your solicitor must ensure it aligns perfectly with the draft lease. They have to coordinate between you, your lender, and the Housing Association to satisfy the UK Finance Mortgage Lender’s Handbook requirements. This is also when you'll make your Stamp Duty Land Tax (SDLT) election. You can choose to pay tax on the full market value upfront or make "staged payments" as you buy more shares. Each option has different long-term financial implications, so clear advice is paramount.
After the landlord approves the final documents for your shared ownership houses, you'll move to the exchange of contracts. This is the point where the deal becomes legally binding. On completion day, your solicitor handles the transfer of funds, and you finally collect the keys to your new home. If you're ready to start this journey, you can get a specialist conveyancing quote to ensure your purchase stays on track.
Staircasing and Beyond: Growing Your Stake in Your Home
The ultimate goal for many residents in shared ownership houses is to eventually own their property outright. This journey is known as staircasing, a process that allows you to buy additional shares in your home as your financial situation improves. Under the 2026 rules, the scheme is more flexible than ever. You can now purchase small 1% increments each year for the first 15 years, or opt for larger chunks starting from 5%. Every time you decide to increase your stake, you'll need a formal valuation from a surveyor registered with the Royal Institution of Chartered Surveyors (RICS). This ensures the price you pay for the new share reflects the current market value at that specific time.
Reaching 100% ownership is a significant milestone. Once you own the property in full, the leasehold structure often falls away, and you may be able to acquire the freehold. At this stage, your relationship with the Housing Association ends, and you transition into traditional homeownership. Having a legal partner with deep experience in residential purchases and sales is invaluable during this final transition to ensure the title is correctly transferred and any remaining rent obligations are legally extinguished.
The Legal Steps of Staircasing
When you staircase, your solicitor will prepare a "Memorandum of Staircasing." This legal document is an amendment to your existing lease that officially records your new, higher percentage of ownership. If you've decided to add a partner or spouse to the deeds at the same time you're buying more shares, you'll also need to complete a "Transfer of Equity." This ensures both parties are legally recognised as owners. As your owned share grows, your monthly rent payments will decrease proportionally, though your service charges will usually remain the same as they cover the maintenance of the entire estate.
Selling Your Shared Ownership House
If you decide to move before reaching 100% ownership, the resale process follows a specific path. You must first give the Housing Association the "Right of First Refusal." This triggers a "Nomination Period," which has been reduced to 4 weeks in the 2026 model. During this time, the landlord will try to find a buyer who meets the eligibility criteria for the scheme. If they don't find a buyer within this window, you can then sell your house on the open market, often as a "back-to-back" staircasing deal where the buyer purchases 100% of the property.
Organising your legal paperwork from the day you move in makes this future sale much smoother. Keeping records of any structural improvements you've made, with the landlord's consent, ensures you get the full benefit of those additions during the RICS valuation. Whether you're buying your first 1% or selling your final stake, having a proactive legal guide ensures every transaction is handled with speed and transparency.
Securing Your Future on the Property Ladder
Owning one of the modern shared ownership houses in the West Midlands is no longer a distant dream but a strategic financial move. By taking advantage of the 2026 reforms, such as lower entry shares and the initial repair period, you're building equity in a home that grows with you. Whether you're navigating the first purchase or planning to staircase to 100%, the right legal support ensures your investment is protected every step of the way.
At Eagle Haus Conveyancing Consultants, we specialise in the unique complexities of this scheme across Staffordshire and the West Midlands. Our team provides a transparent fixed-fee structure, so you won't face any hidden costs during your move. As we are regulated by the SRA through our partnership with Taylor Rose, you can move forward with complete peace of mind. We pride ourselves on being modern guides who blend professional authority with a personal, supportive touch.
Ready to take the next step? Get a Reassuring Shared Ownership Quote from Eagle Haus Conveyancing Consultants today. Your journey to full homeownership starts with a single, confident step, and we're here to guide you home.
Frequently Asked Questions
Can I buy a shared ownership house if I have owned a property before?
You can purchase a shared ownership home even if you have owned a property previously. This scheme is often a lifeline for "second-steppers" who have experienced a relationship breakdown or a significant change in financial circumstances. You must have sold your previous home before completing your new purchase. Additionally, your household income must remain below the £80,000 threshold to qualify for the scheme outside of London.
Do I have to pay Stamp Duty on a shared ownership property in 2026?
Stamp Duty Land Tax (SDLT) applies if the property value exceeds the current thresholds. You have two choices: pay tax on the full market value upfront or pay in stages as you buy more shares. Many buyers choose the staged approach to lower initial costs. However, if you are a first-time buyer, you might be eligible for relief on the first £425,000 of the property's total value.
Is it harder to get a mortgage for a shared ownership house?
Securing a mortgage for shared ownership houses isn't necessarily more difficult, but you'll have fewer lenders to choose from. Many high-street banks offer specific products for this scheme. Lenders will assess your ability to cover the mortgage, the subsidised rent, and the service charges combined. Working with a specialist broker can help you find the most competitive rates for your specific financial situation in the West Midlands.
Can I staircase to 100% ownership on all shared ownership houses?
Most leases allow you to staircase to 100% ownership, but there are exceptions. Properties in "Designated Protected Areas," often in rural Staffordshire or Shropshire, may be capped at 80% to ensure they remain affordable for future local buyers. Your solicitor will check your specific lease for any such restrictions during the conveyancing process. Knowing these limits early on helps you plan your long-term property goals with total confidence.
What happens if I want to make improvements to my shared ownership home?
You must obtain written consent from your Housing Association before making structural alterations like extensions or conservatories. Minor decorative changes usually don't require permission. When you staircase or sell, a RICS surveyor will value the property. They will often provide two figures: one with the improvements and one without. This ensures you benefit from the value added by your own investment rather than paying for that value twice.
Are shared ownership houses only available for new-build properties?
Shared ownership isn't limited to new-build developments. You can also purchase "resale" properties where the current owner is selling their existing share. These homes often come with established communities and mature gardens. It's important to check the lease terms on resales, as they may follow older models rather than the 2026 reforms. Resales still require the same eligibility checks and specialist legal advice as any new-build purchase.
Can I rent out my spare room in a shared ownership house?
You are generally permitted to take in a lodger or rent out a spare room whilst you live in the property. However, subletting the entire house is strictly prohibited under the terms of the lease until you own 100% of the property. This rule ensures the scheme continues to support people who need a primary home to live in. Always check your specific lease or contact your landlord for confirmation.
What are the typical first time buyer conveyancing fees for these schemes?
While first time buyer conveyancing fees for shared ownership houses can be slightly higher than standard purchases, they reflect the additional legal work involved. Your solicitor must liaise with the Housing Association and review complex lease clauses that don't exist in traditional sales. At Eagle Haus Conveyancing Consultants, we provide a transparent, fixed-fee quote so you can budget accurately for your move without worrying about unexpected legal costs later.
Comments